Published -
August 31, 2026
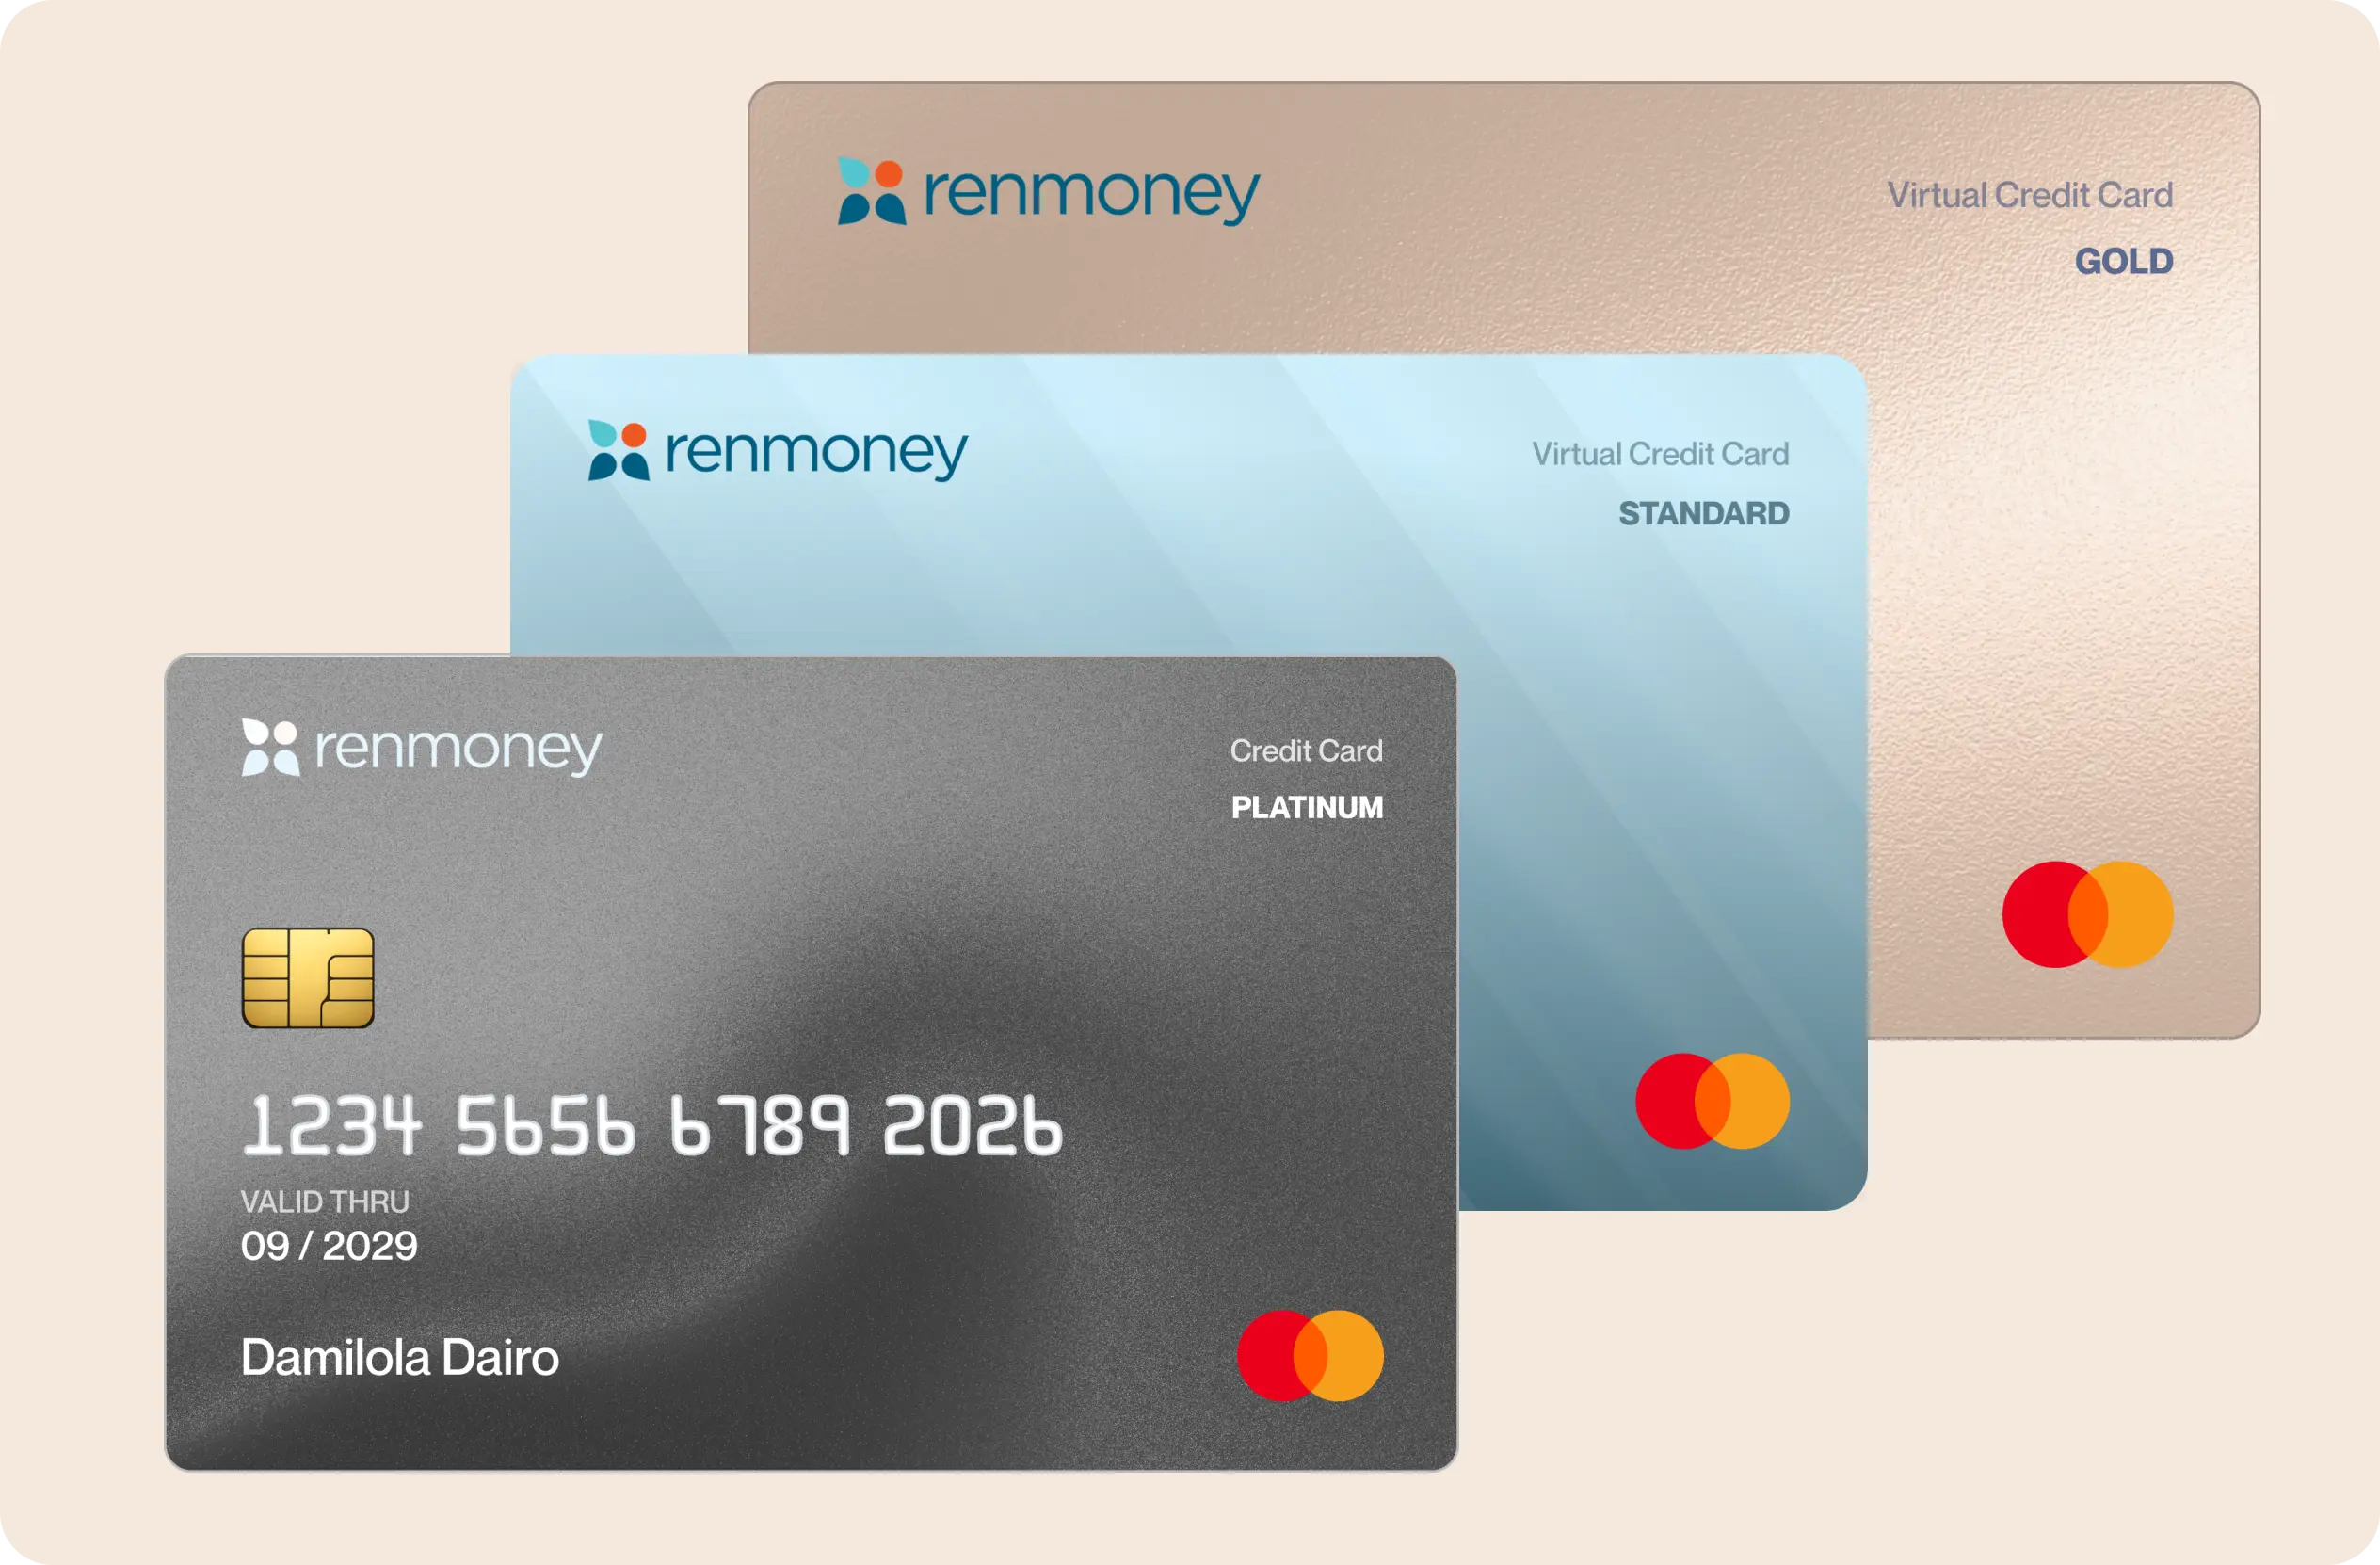
Note: This is an independent product design exploration created using Renmoney as a case study. The concept was developed in response to a design challenge and is intended to demonstrate my approach to product thinking, user experience design, and solving problems that sit across both digital and physical experiences.
You order a new debit card, excited to use it for online payments and everyday spending. Days later, a dispatcher calls, but you can't find each other, the delivery fails. When the card finally arrives, you put it somewhere safe and never activate it.
For fintechs, this is a silent leak in the customer journey: every failed delivery is a card that never activates, and every inactive card is a customer who never experiences the product's value.
This project explores two connected moments: helping physical cards arrive successfully, and helping customers activate them while motivation is highest.
Ordering a card should be simple, receiving it predictable, activating it effortless. But the journey between request and first transaction has real drop-off points. I focused on two connected problems:
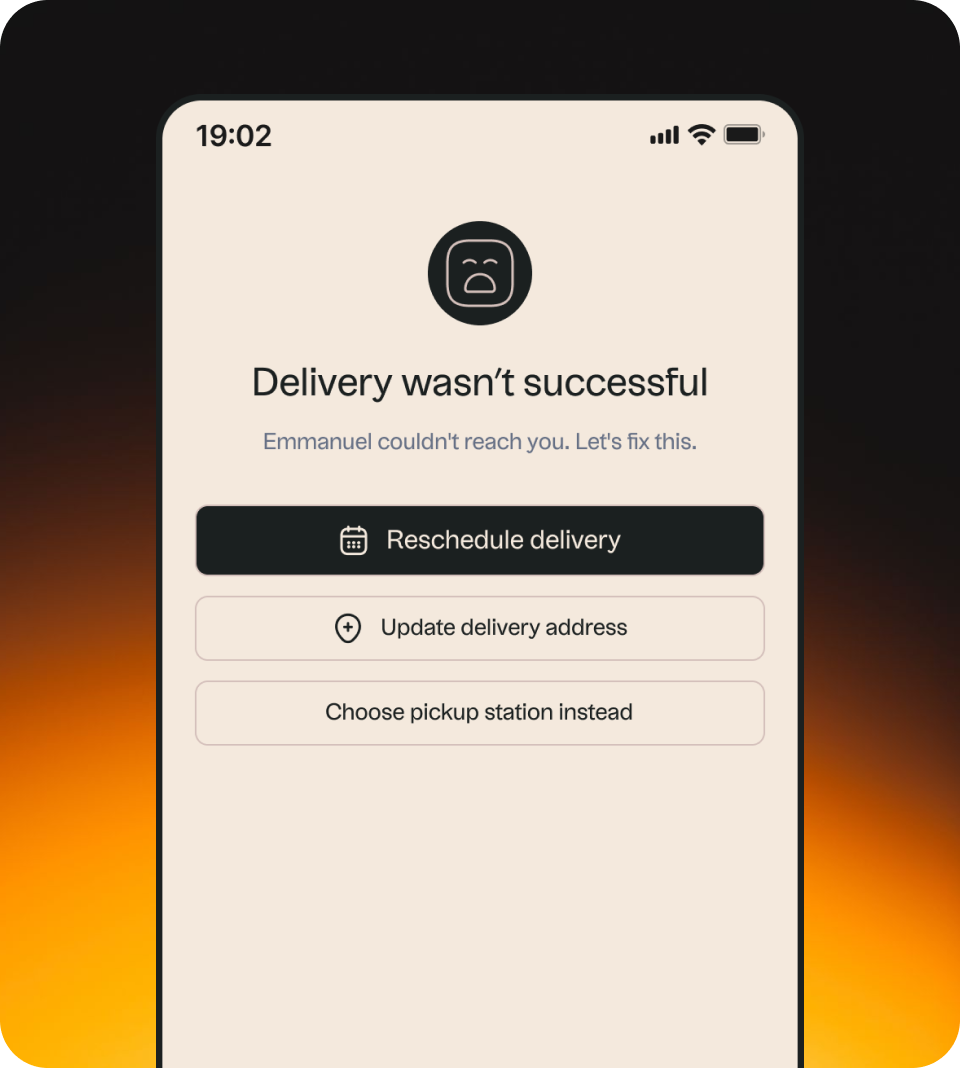
A physical address isn't always enough to locate a customer, a market stall, an unmarked compound, a location easier described by landmark than street name. A failed delivery means the customer never receives the card, never activates it, and never transacts.
Receiving a card doesn't guarantee use. The customer may intend to activate it later, get distracted, or simply not feel urgency to complete another setup flow.
These are connected: a customer can't activate a card they never receive, and once a card arrives, that handover moment is a valuable, underused opportunity to drive activation.
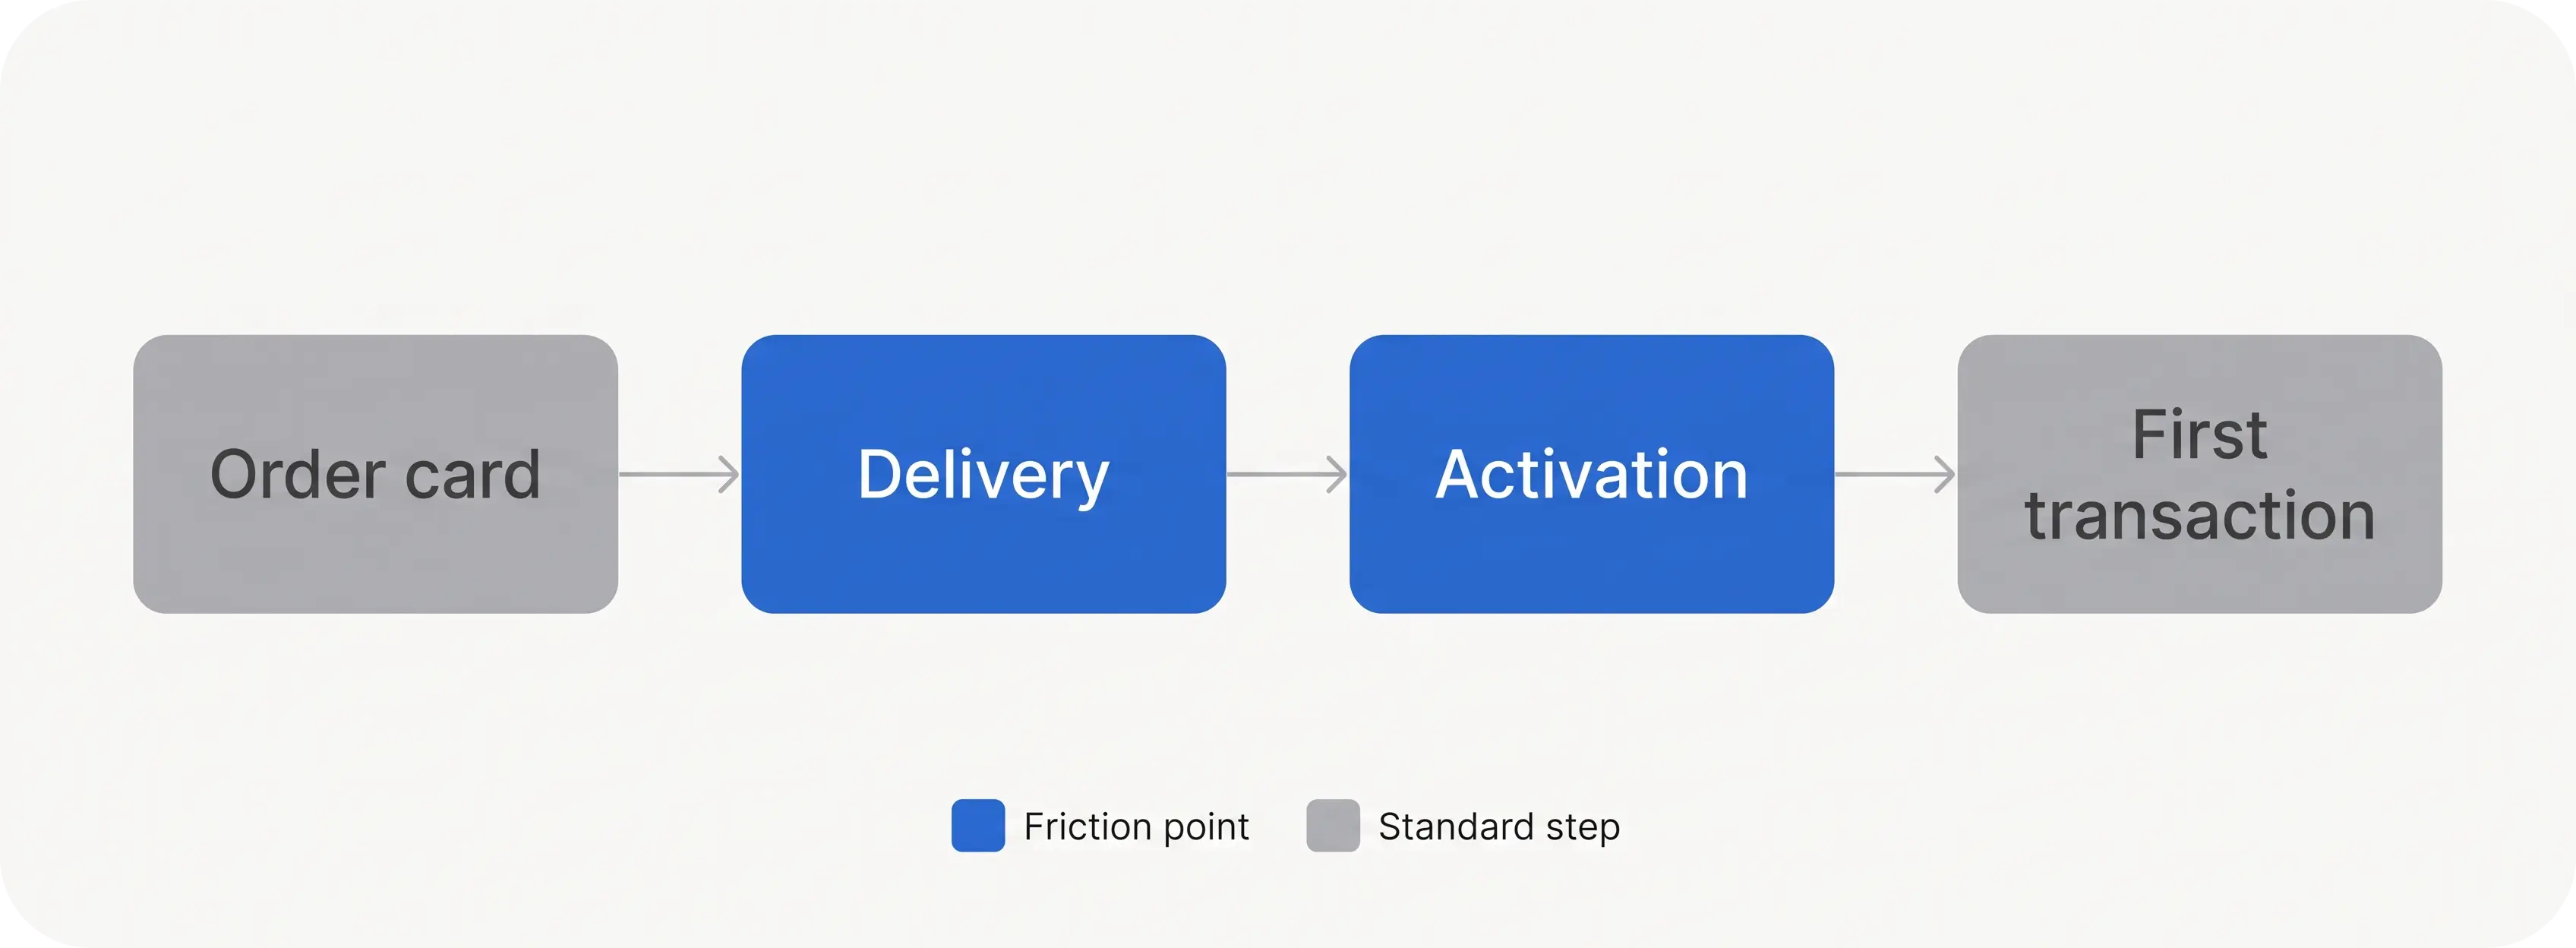
Physical cards only create value when used. Card activation rate is widely tracked as a core fintech metric precisely because unactivated cards represent lost onboarding investment (Interexy, "How to Launch a Neobank in 2026").
Before designing, I looked at how other fintechs handle the journey from card request to first use, focused on one question: when should a customer set their PIN and activate their card?
Kuda lets customers create their PIN during the request flow, before delivery: Request card → Create PIN → Enter delivery details → Wait → Activate on receipt. (Kuda Help Center, "Request A Kuda Card") This moves setup earlier and reduces post-delivery work, but it separates PIN creation from physical ownership, the customer may create a PIN, wait days, even forget said PIN set earlier and still need a separate activation step later. It's a reasonable, efficient decision, not a flaw, but it raised a different question for me: what if the moment of physical delivery was also the moment of activation?
Moniepoint takes the opposite approach in my experience using it: the customer completes verification and PIN setup only after physically receiving the card. More steps happen post-delivery, but activation is more directly tied to holding the card.
Comparing these two approaches wasn't about finding a "correct" answer, it was about deciding where each part of the experience should live: before delivery, after delivery, or at the exact moment the card changes hands.
My answer to "what's the most natural moment to activate a card" was: the moment the customer receives it. Motivation is already highest right then. Instead of asking customers to remember activation later, I explored making activation part of the delivery moment itself.
The brief described Nigerian users with varying digital confidence and living situations. Rather than designing for an idealized customer with a perfect address, I built four personas representing different realities:
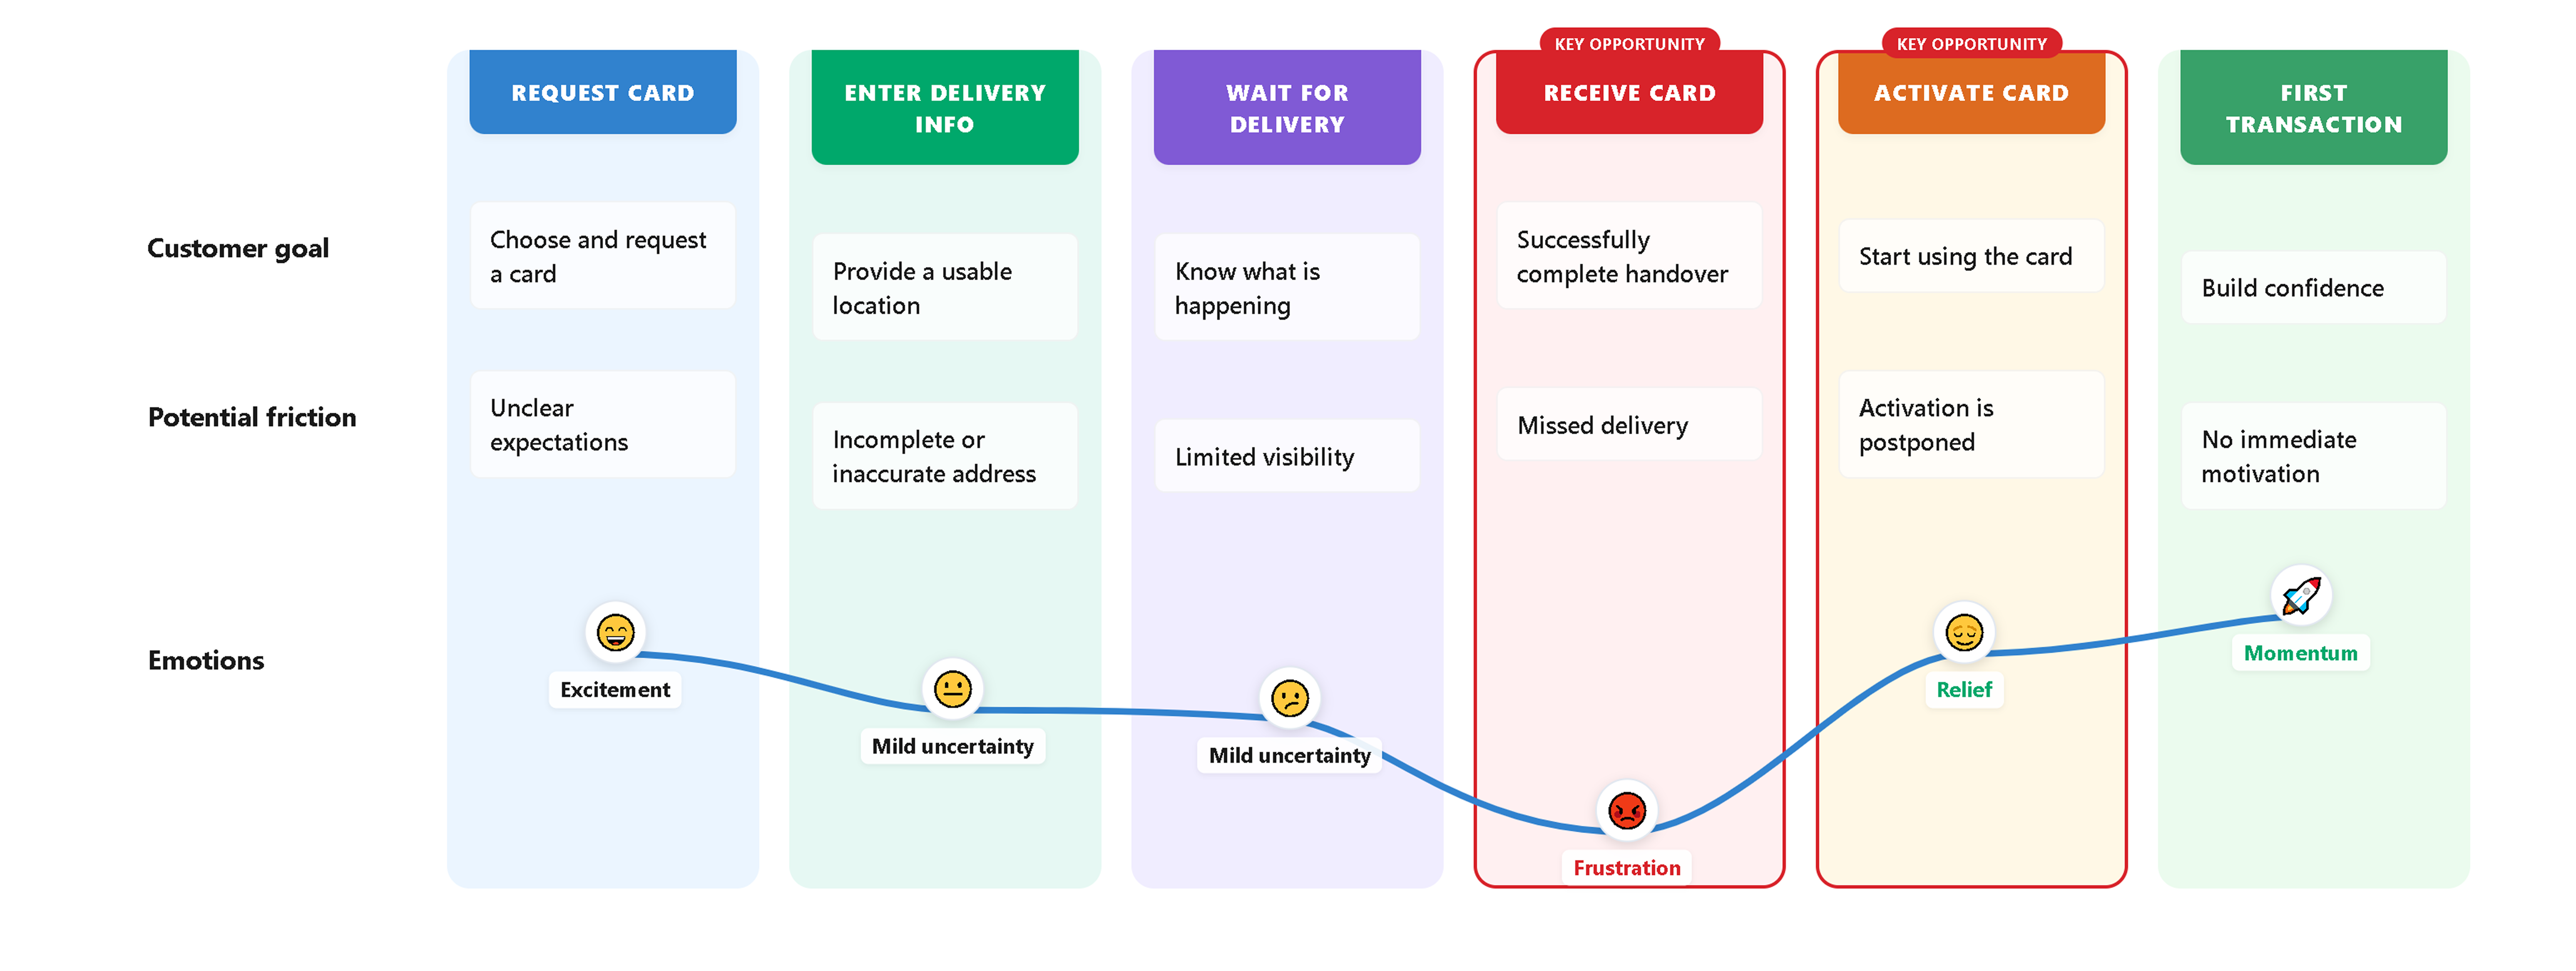
The strongest opportunities: improving delivery success, and closing the gap between receiving and activating.
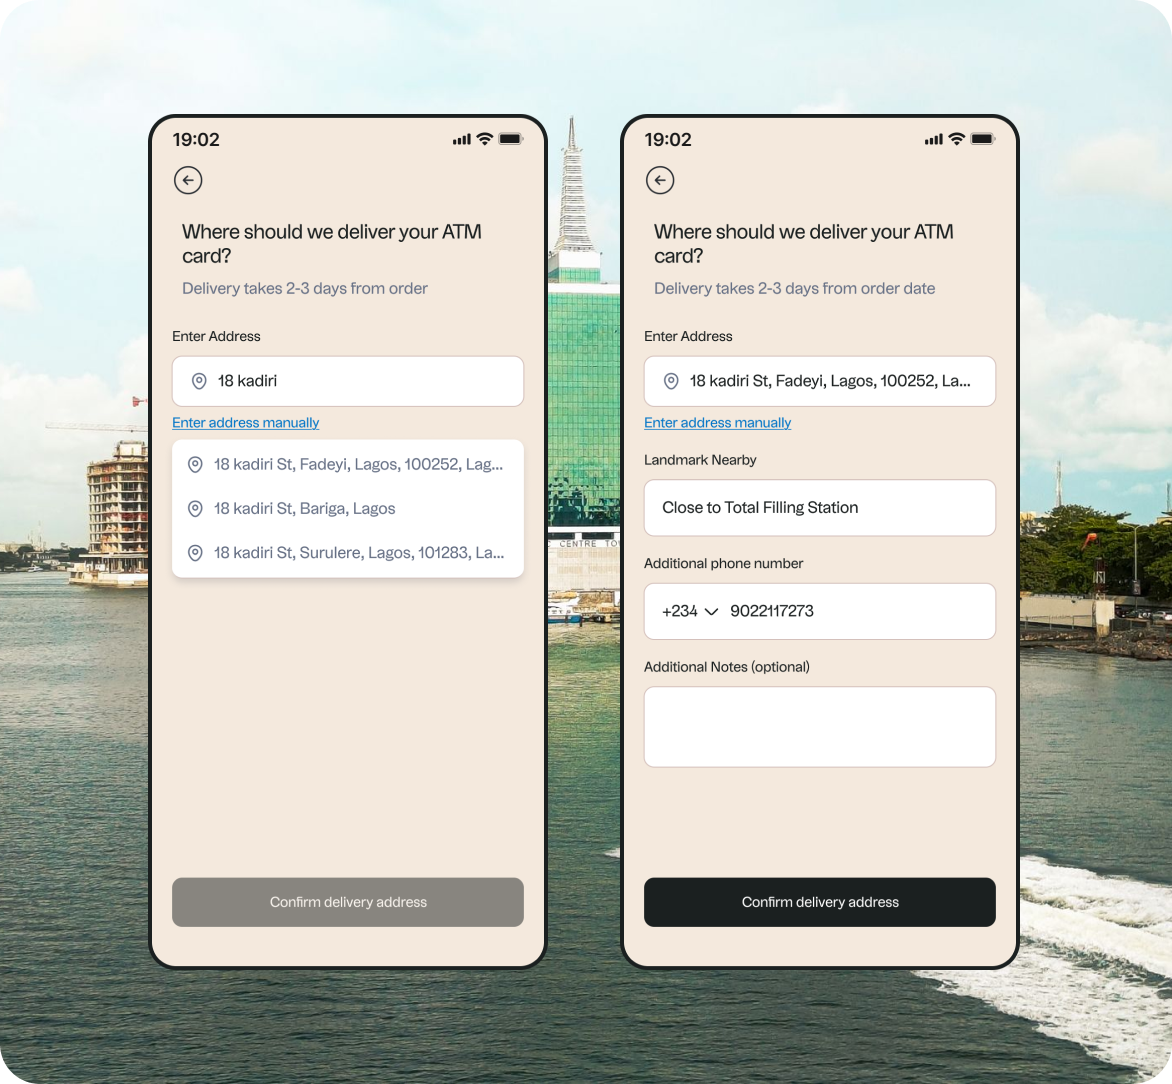
A standard address form assumes every customer has a clear, standardized address. That's not always true. A better approach combines map location, address details, a landmark, an additional phone number, and delivery notes, so a customer can describe their location the way they naturally would ("close to Total Filling Station," "behind the blue gate opposite the church") instead of forcing a street address that may not exist.
The bigger opportunity wasn't redesigning the activation screen, it was reconsidering when activation happens. The default mental model is "receive the card now, activate it later," but later isn't reliable.
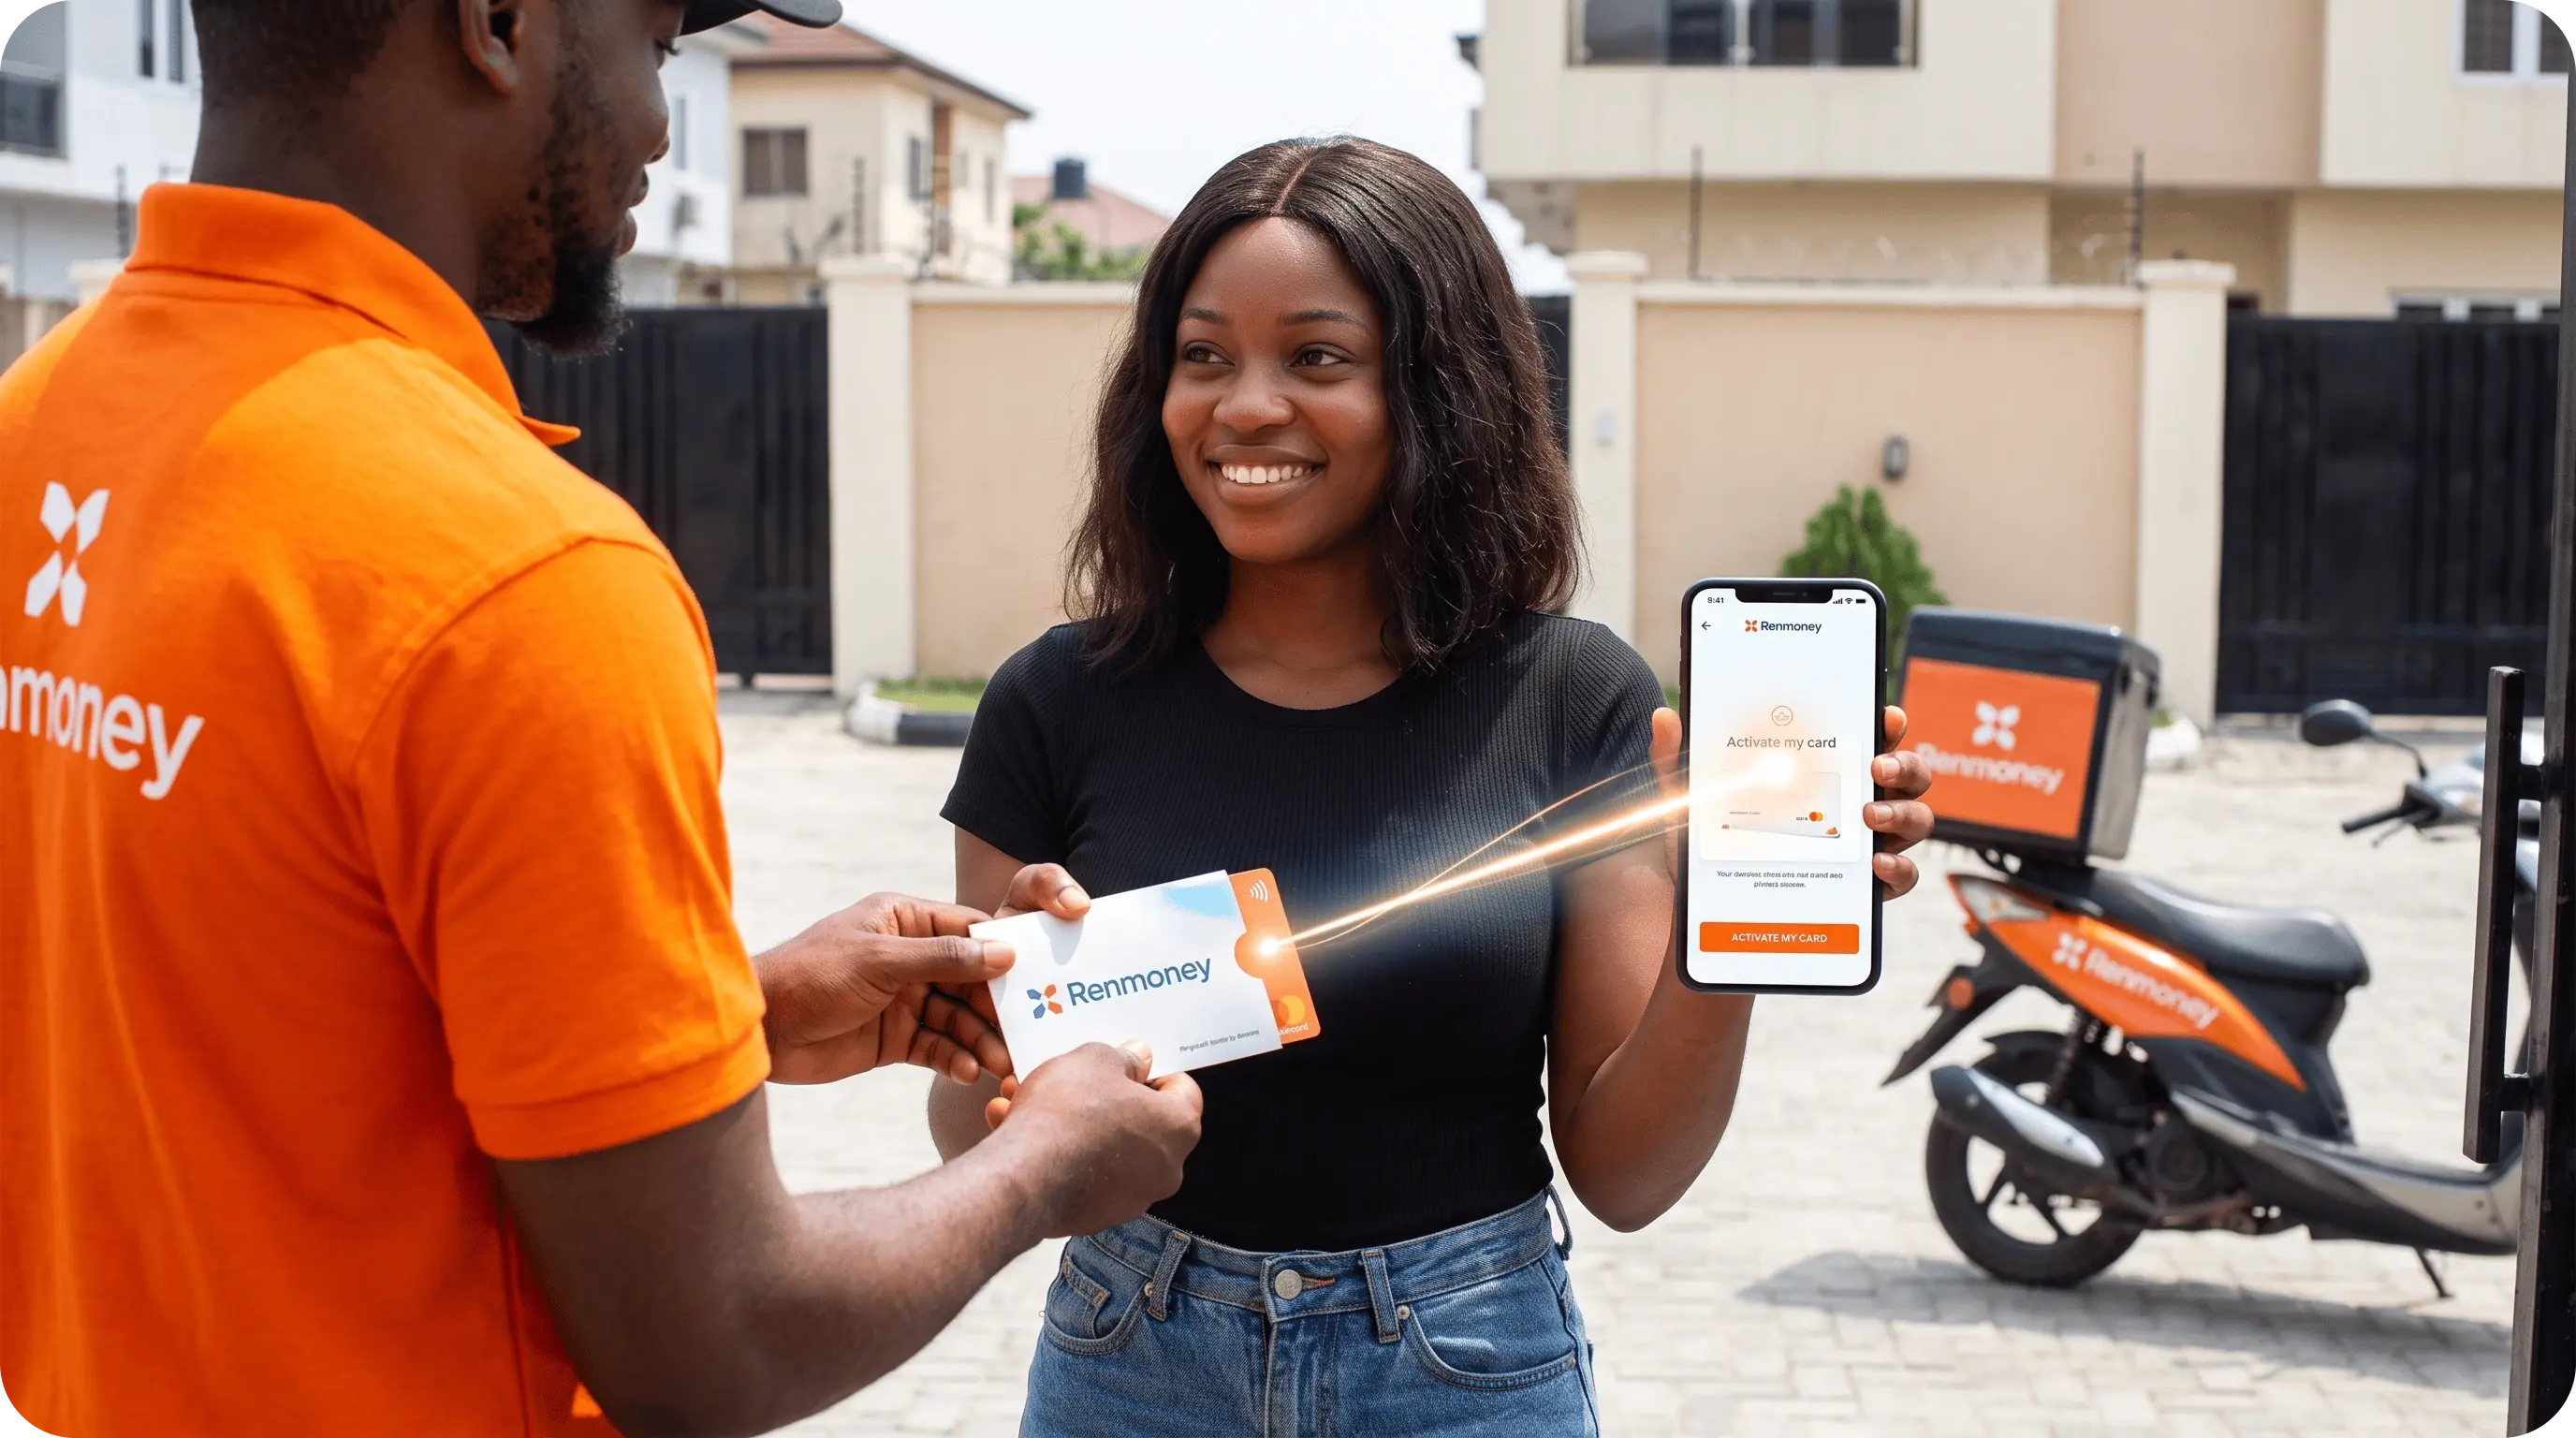
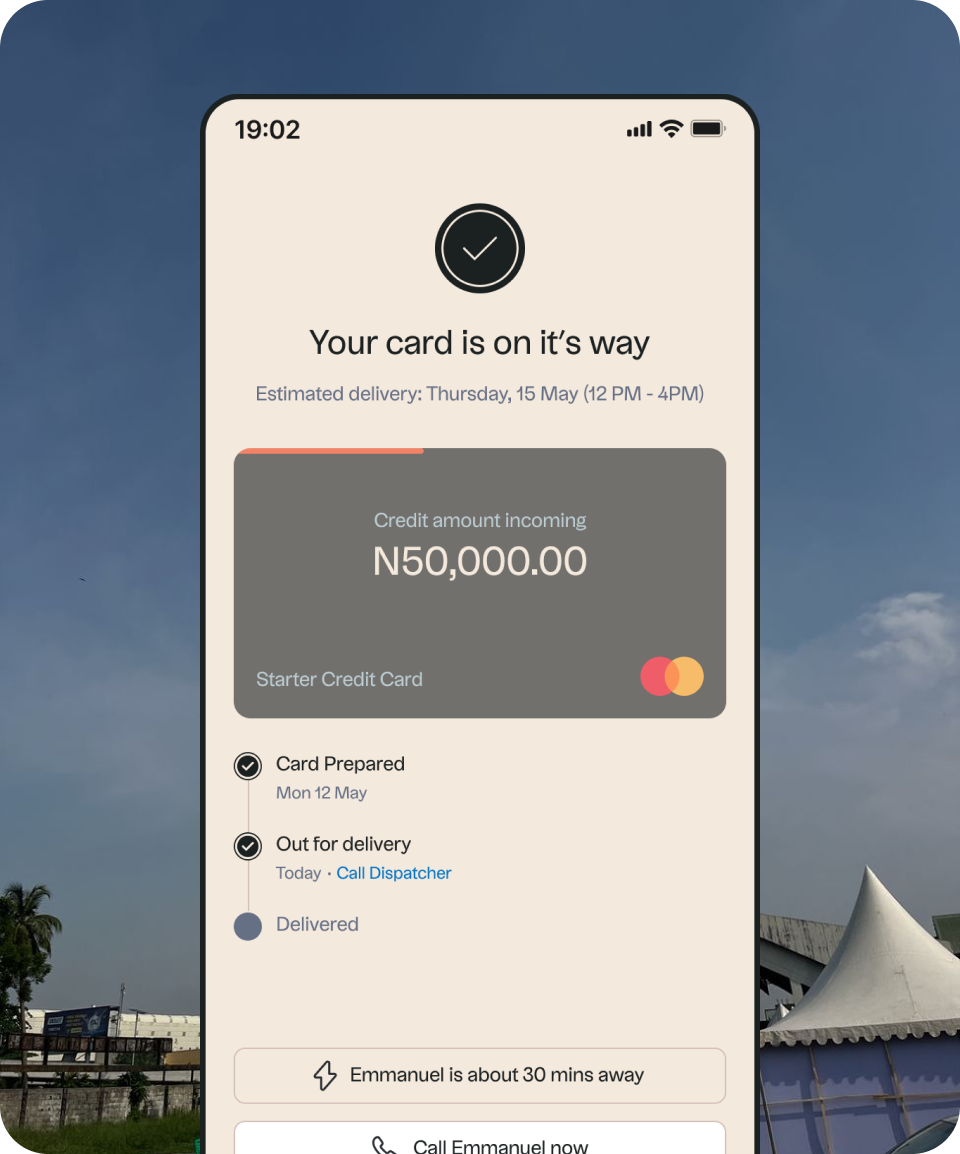
The dispatcher-triggered activation flow: the dispatcher calls to confirm the right person is available, the customer shows up, opens their app, confirms the card has physically arrived, creates their PIN, the card activates, and the dispatcher hands it over, all while the customer is already engaged in the delivery moment.

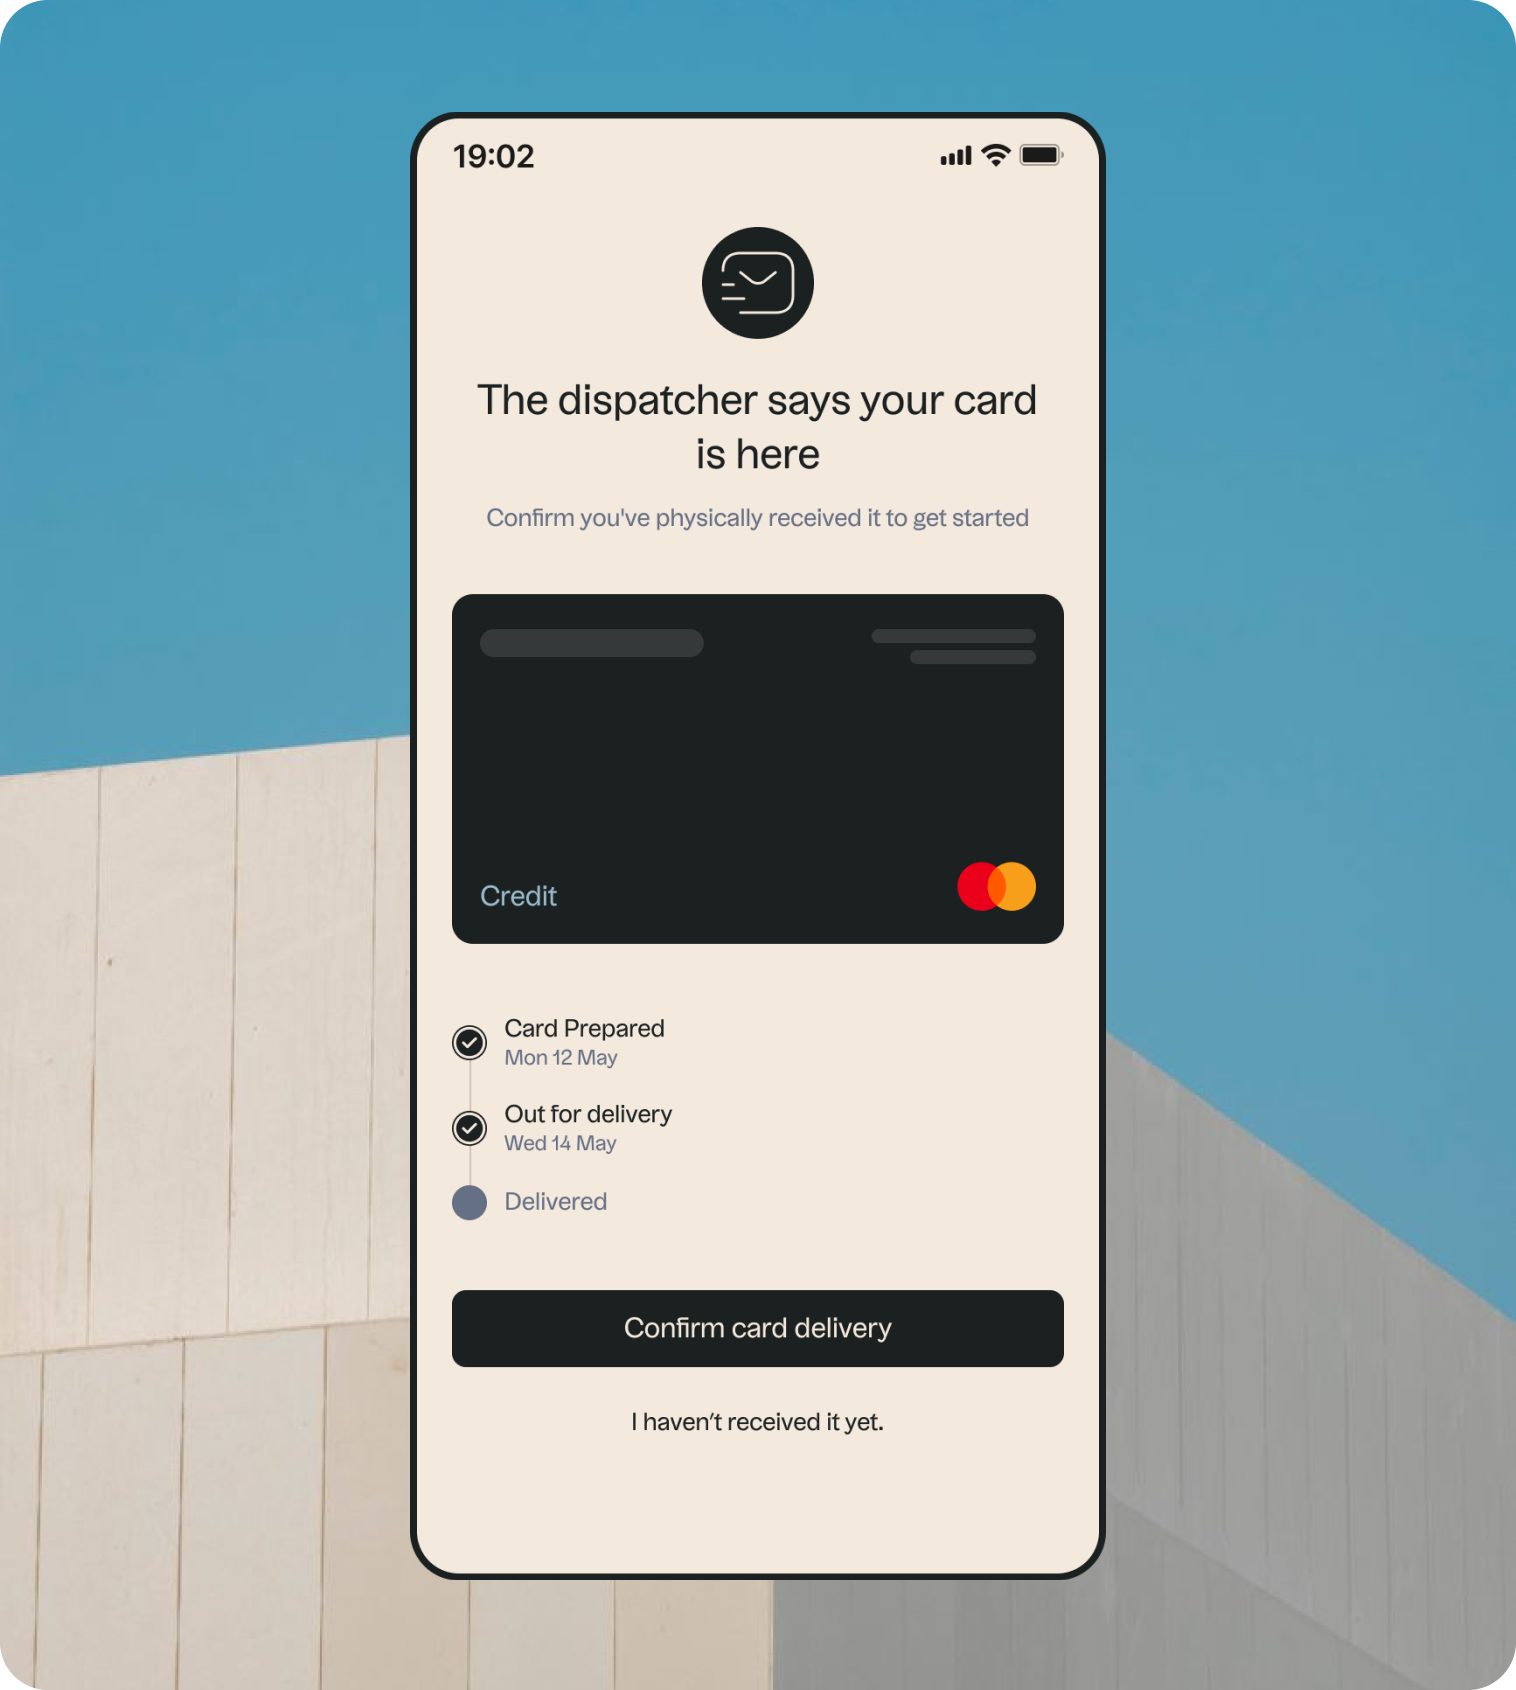
Confirming physical ownership: the app shows the delivery timeline (Prepared → Out for Delivery → Delivered), and when the dispatcher arrives, the customer taps "Confirm card delivery," bridging the physical handover into the digital activation flow.
Creating a PIN: intentionally short, Create PIN → Confirm PIN → Done, with a brief security note that Renmoney staff will never ask for it.
Encouraging the first transaction: immediately after activation, a time-limited incentive (e.g., "Use your card within 24 hours and get ₦300 cashback") lands exactly when motivation is highest, moving the customer from I have a card to I know how to use my card.
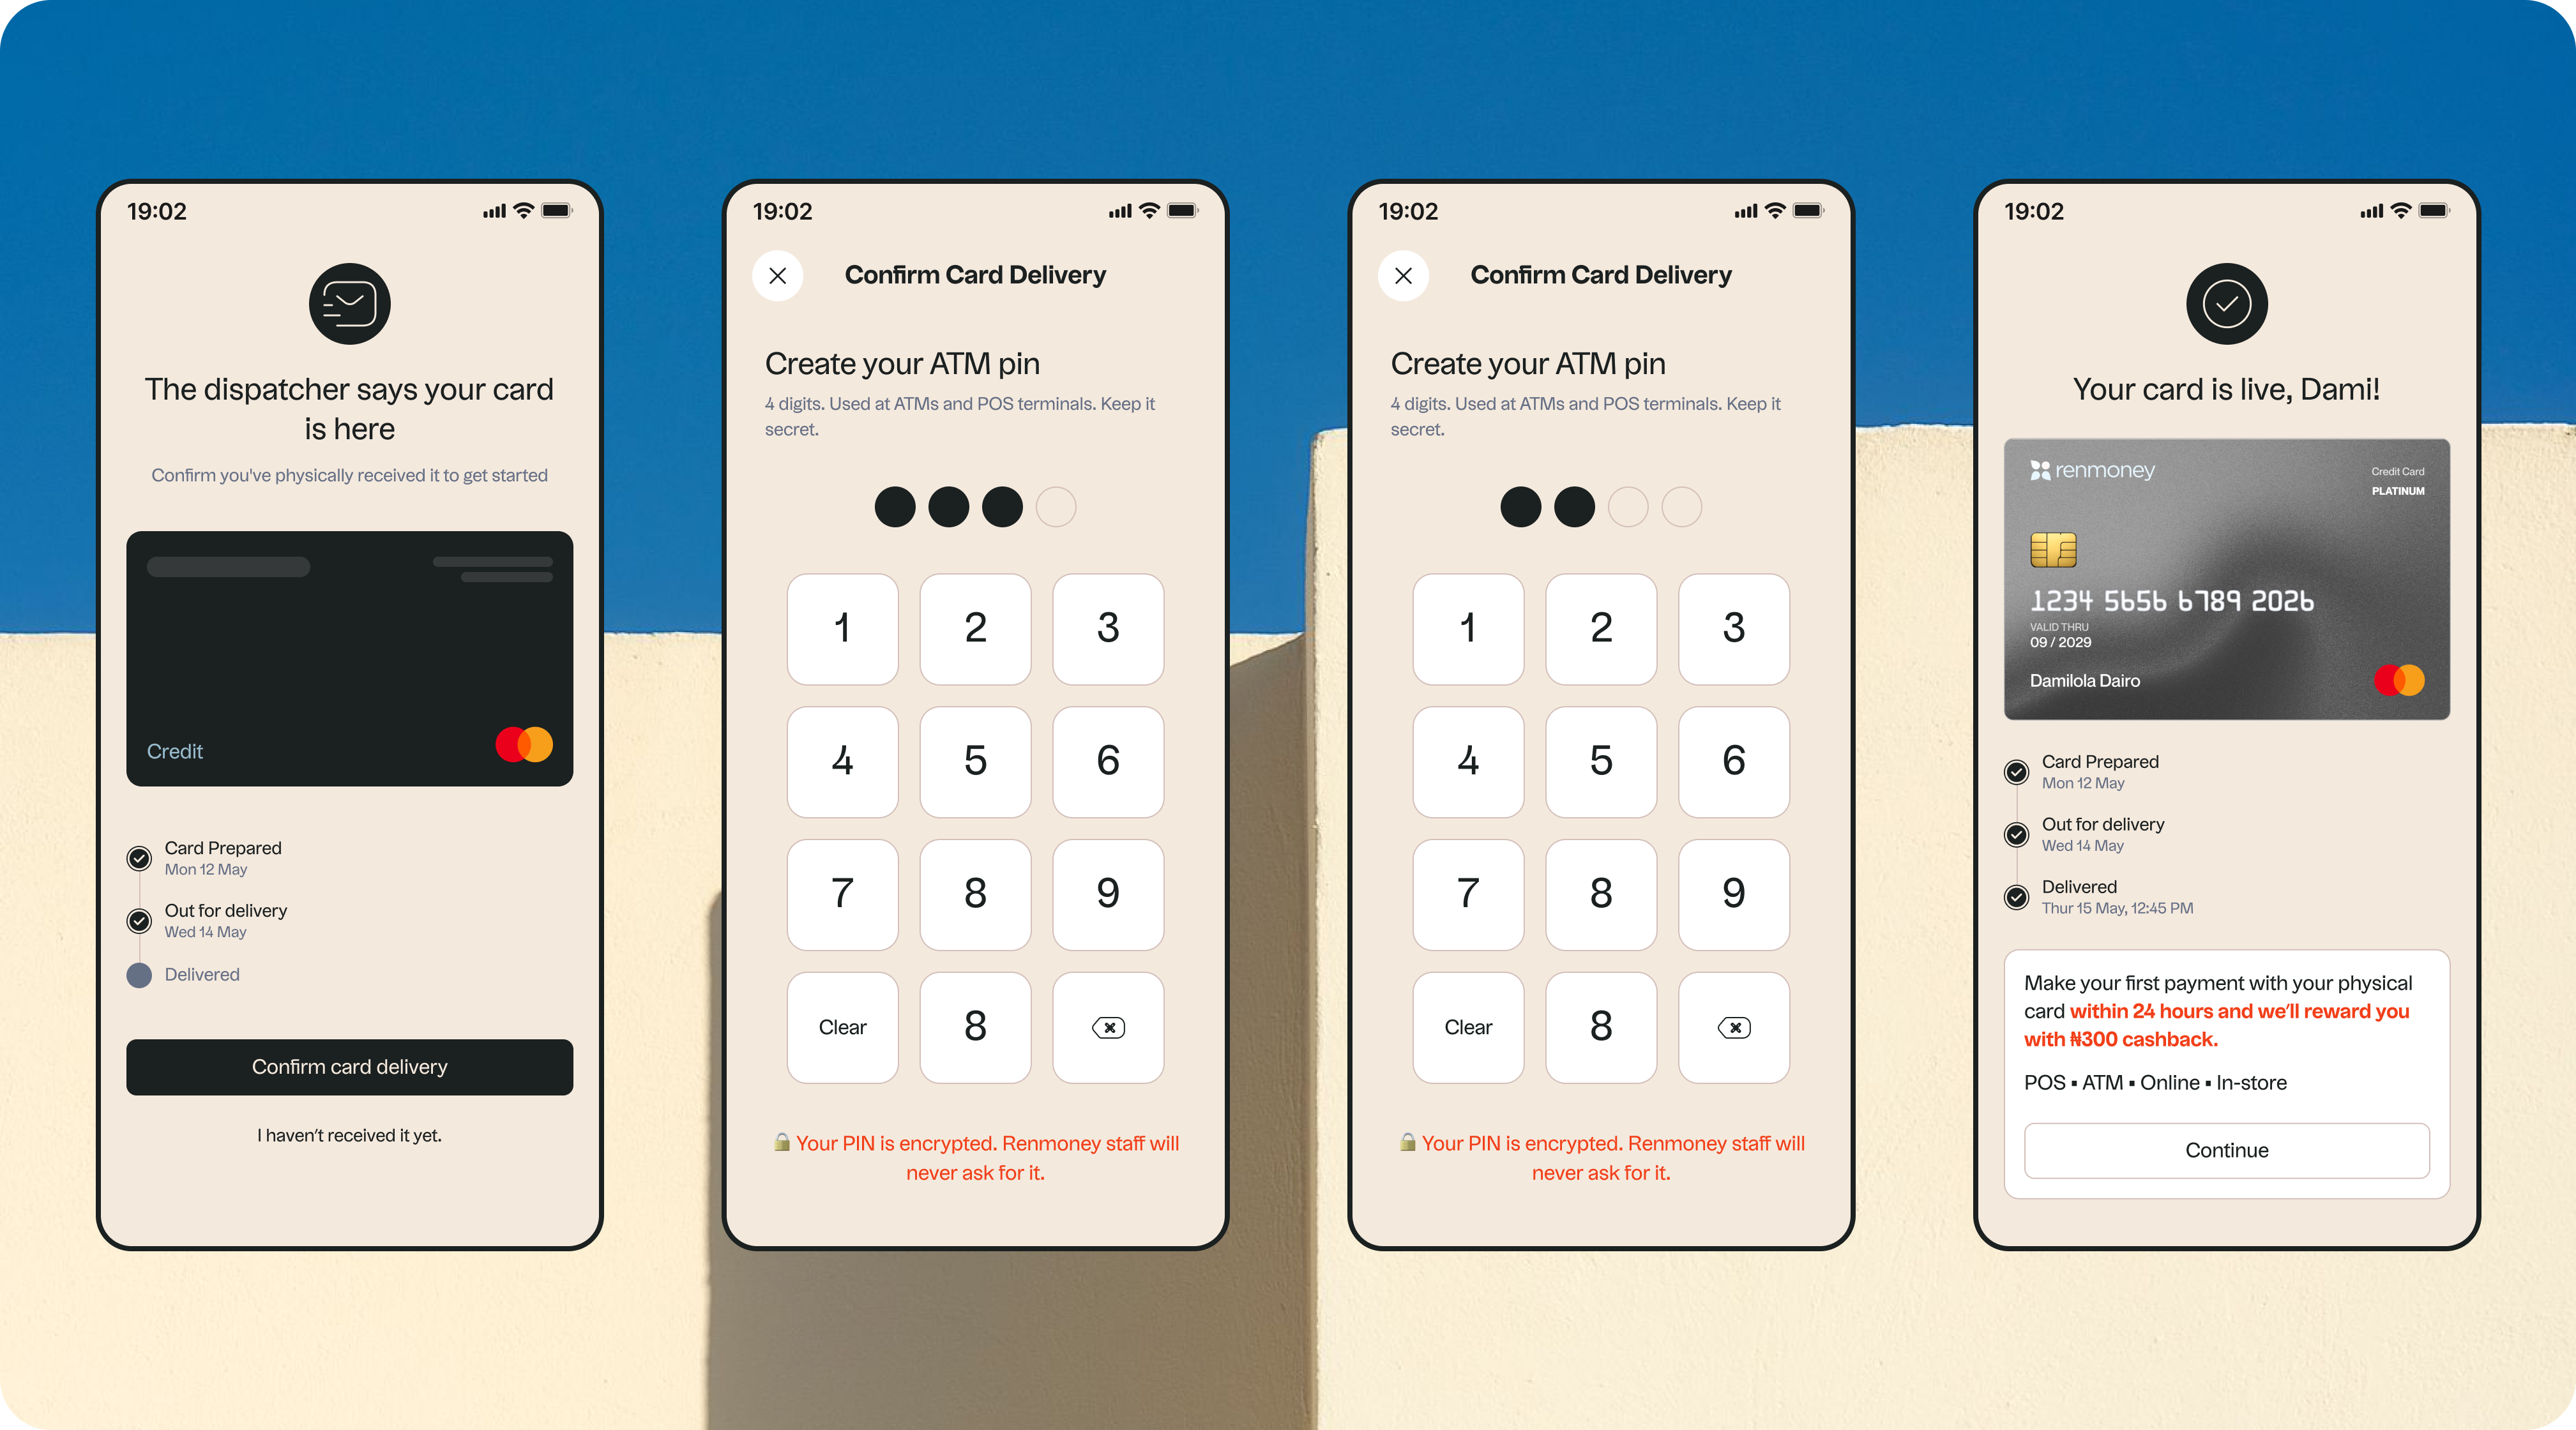
Better location info before delivery → tracking and dispatcher coordination during delivery → in-app confirmation at handover → PIN creation and activation immediately after → a first-use incentive right after that.
Kuda showed that PIN creation doesn't have to wait for delivery, a genuinely useful pattern. But instead of asking "how much setup can happen before delivery," I asked what's the most natural moment to complete activation. For this exploration, that moment is when the customer confirms the card is physically in hand.
The sequence becomes Receive → Confirm → Activate → Use, instead of Set up → Wait → Receive → Remember to activate → Maybe use. This isn't a claim that one approach is universally better, different products have different operational constraints, but for the specific problem of closing the gap between delivery and activation, this was the design decision that made sense.
All targets below are proposed, not measured, this is a concept exploration, not a shipped product with live data.
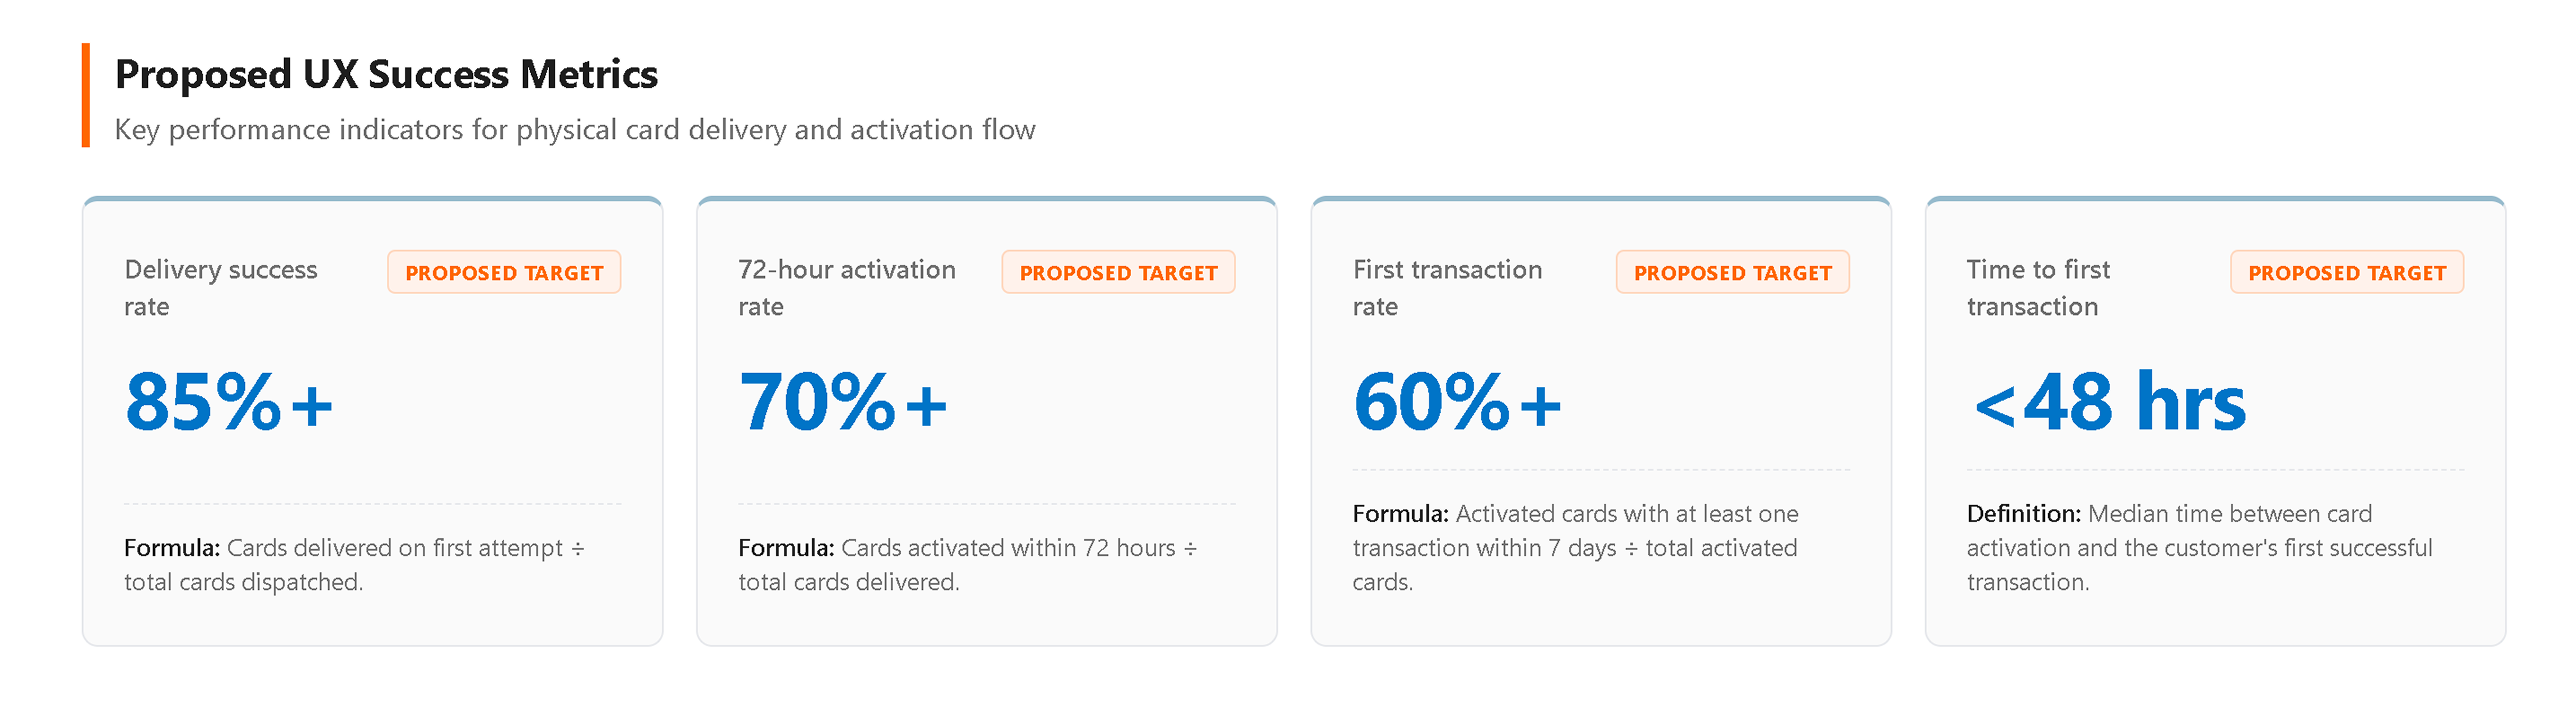
I started this thinking about activation as an interface problem. Working through the journey showed me it's a service problem, delivery logistics, operational workflows, and human interactions all shape whether a customer ever becomes active. The strongest activation flow may not be another screen, it may be redesigning the service around the moment the customer actually receives the product.
The question I was left with: if the customer is already holding the card, why ask them to remember to activate it later?